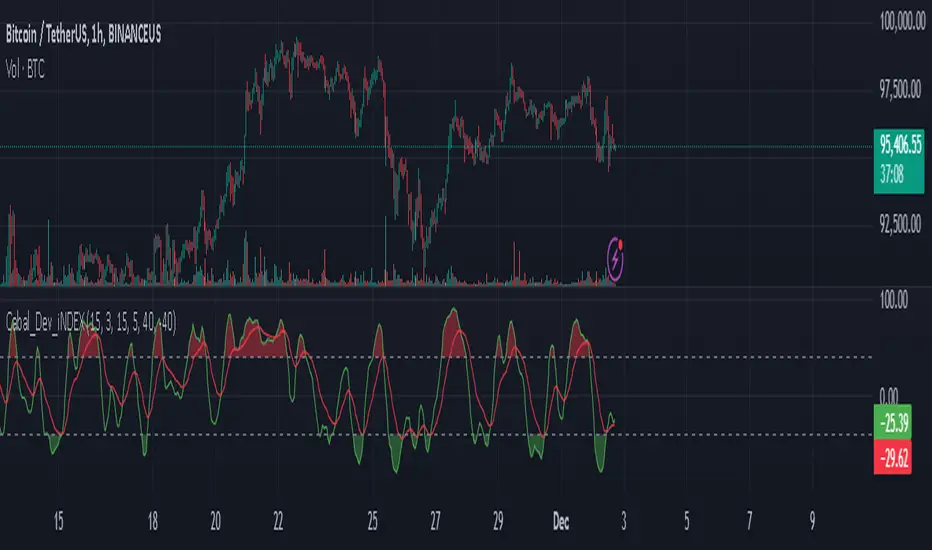
RvDiv Regular Divergence (Daily)Rv-Div — Regular Divergence (Daily)
Rv-Div marks confirmed regular divergences on the daily chart and draws the line that connects them, so you can see the structure the signal is based on instead of trusting an arrow.
**What it does**
A bullish divergence is price making a lower low while the oscillator makes a higher low: price is still falling, but with less force behind it. A bearish divergence is the mirror image — a higher high in price against a lower high in the oscillator.
Rv-Div marks the exact candle that confirms the divergence, draws the line between the two pivots it used, and can fire an alert.
**The problem it solves**
Most divergence tools compare each new pivot against the immediately previous one. That works until a small wrinkle appears between the two lows that actually matter — and then the line gets drawn between the wrinkle and the new low instead of between the two real lows. The divergence you see on screen is not the one your eye would have drawn.
Rv-Div compares each new pivot against the last N pivots, not just the previous one, and keeps the one that forms a valid divergence. That is what the eye does: connect the two lows that matter, skipping the noise in between.
It also spends each anchor. Without that, one old pivot gets reused against every new pivot that appears, and you end up with several lines fanning out from the same point — the same divergence counted three or four times, which inflates any count you make of them. Here, once an anchor is used it is discarded along with everything older.
**Quality filters**
Not every pair of pivots deserves to be called a divergence. Four filters, all adjustable:
- Minimum price difference between the two extremes, measured in ATR, so it travels across symbols and volatility regimes instead of using a fixed percentage.
- Minimum difference between the two oscillator pivots.
- Both oscillator pivots on the correct side of zero.
- Minimum and maximum bar separation between the two pivots.
**Settings**
Three oscillators to choose from — Awesome Oscillator, MACD histogram, and a linear-regression momentum. All three are public-domain formulas.
The pivot definition (bars to the left and right), the quality filters, the two EMAs, the colours, the label size and the line width are all adjustable. The default values are the ones I use on the daily chart.
**How to use it**
Daily chart only. The indicator says so on screen if you load it on any other timeframe.
Set alerts to **Once per bar close**. A forming candle keeps changing until it closes, and a divergence is not confirmed until then.
**Dropping to a lower timeframe to confirm**
The signal is a daily signal, but you do not have to take it blind on the daily close. Once the daily marks the entry, drop to 4h and wait for a break of the local high followed by a pullback — or go from 4h down to 1h and look for the same thing. You give up a little of the move in exchange for not entering into a candle that is still falling.
This is deliberately not built into the indicator. It is a judgement call, and judgement calls belong to the trader, not to a script that has to work the same way on every symbol and every market.
**What it does not do**
It does not manage exits. It marks an entry candle and nothing else — no targets, no stops, no position sizing. Those decisions are yours.
It is not a standalone system. A divergence tells you that momentum is fading, not that the trend has turned. What you do with that information is where your own judgement goes.
**About the confirmation delay**
A pivot does not exist until the required bars have closed to its right, so the signal arrives with that delay. This is deliberate. Removing it would mean signalling on unconfirmed pivots, which look excellent in hindsight and vanish in real time.
Historical signals do not repaint: once a pivot is confirmed, it stays confirmed. The forming candle is the only thing that can change, which is why alerts should be set to bar close.
---
**Español**
Rv-Div marca divergencias regulares confirmadas en gráfico diario y dibuja la línea que las une, para que veas la estructura en la que se apoya la señal en lugar de fiarte de una flecha.
Una divergencia alcista es el precio haciendo un mínimo más bajo mientras el oscilador hace un mínimo más alto: sigue cayendo, pero con menos fuerza detrás. La bajista es la imagen espejo.
La diferencia con la mayoría de detectores de divergencia está en el trazado. Casi todos comparan cada pivote nuevo con el inmediatamente anterior, y en cuanto aparece una arruga entre los dos suelos que de verdad importan, la línea sale mal dibujada. Rv-Div compara contra los últimos N pivotes y se queda con el que forma la divergencia válida — que es lo que hace el ojo. Además consume cada ancla, así que un mismo pivote antiguo no se reutiliza una y otra vez generando varias líneas en abanico desde el mismo punto.
Cuatro filtros de calidad ajustables (diferencia mínima de precio en ATR, diferencia mínima del oscilador, ambos pivotes del lado correcto del cero, y separación mínima y máxima), tres osciladores a elegir, y todo el aspecto configurable.
Solo diario. Alertas configuradas como "Una vez por barra al cerrar".
**Bajar a una temporalidad menor para confirmar.** La señal es del diario, pero no hace falta tomarla a ciegas en el cierre diario. Cuando el diario marca la entrada, se puede bajar a 4h y esperar una ruptura del máximo local con su retroceso — o de 4h bajar a 1h y buscar lo mismo. Se cede un poco del movimiento a cambio de no entrar en una vela que todavía viene cayendo. Esto no está metido en el indicador a propósito: es criterio del operador, y el criterio no se le delega a un script que tiene que funcionar igual en todos los símbolos.
No gestiona salidas ni es un sistema completo: marca la vela de entrada y nada más. Una divergencia dice que el impulso se está agotando, no que la tendencia ya giró.
El retraso de confirmación es deliberado: un pivote no existe hasta que cierran las velas que lleva a su derecha. Quitarlo significaría señalar sobre pivotes sin confirmar, que se ven perfectos en el pasado y desaparecen en vivo. Las señales históricas no repintan. אינדיקטור

Liquidation Magnet [Quantum Algo]Liquidation Magnet
═══════════════════════════════════════════════
🔶 OVERVIEW
Liquidation Magnet estimates where over-leveraged long and short positions are likely to be liquidated, builds decaying volume-weighted clusters at those levels, and renders them as heat ladders directly on your chart. A gold magnet beam locks onto the strongest nearby pool, purge flashes mark the moment price sweeps through a cluster, and a statistics panel tracks how often those sweeps actually reverse on the exact symbol and timeframe you are trading.
The idea is simple and powerful: price does not wander randomly — it is drawn toward liquidity. The largest pockets of forced orders sit where crowded positions get liquidated. This tool maps those pockets, weighs them, and watches them get consumed.
Important honesty note, up front: every level in this indicator is an ESTIMATE derived from price structure and typical leverage tiers. This script does not read exchange liquidation feeds or order-book data, and no indicator on this platform can. Anyone claiming otherwise is guessing with extra steps. This tool guesses transparently — and then measures itself.
═══════════════════════════════════════════════
🔶 WHAT IS A LIQUIDATION MAGNET?
When traders open leveraged positions near a swing high or swing low, their liquidation prices sit at fixed, mathematically determined distances from their entries. A crowd of 25x longs opened near a swing low will be liquidated roughly four percent below it. A crowd of 50x shorts opened near a swing high will be liquidated roughly two percent above it.
Those liquidation prices are where forced market orders wait. Forced orders are fuel. Markets are drawn toward fuel — sweep the pool, fill the orders, and very often reverse once the fuel is spent. That pull is the "magnet."
═══════════════════════════════════════════════
🔶 WHY IS THIS ORIGINAL?
1. Cluster model, not static lines. Swing anchors project liquidation estimates through four leverage tiers (10x, 25x, 50x, 100x, each toggleable). Nearby estimates MERGE into clusters whose mass grows with the volume behind the anchoring swing — scattered guesses become weighted zones.
2. Living decay engine. Positions close, stops move, the crowd rotates. Every cluster loses mass each bar and dies when it fades — or the instant price sweeps through it and consumes it. The map you see is current, never a museum of stale lines.
3. Purge detection with self-auditing statistics. When price trades through a pool, the tool prints a purge flash and then measures what happened next. The dashboard reports the ten-bar reversal rate after upward and downward purges — computed on your chart, shrunk toward neutral at small sample sizes, with a Wilson lower bound available in tooltips. The indicator grades its own thesis in public.
4. The magnet beam. Among all pools within reach, the strongest (mass discounted by distance) is highlighted with a gold beam from live price — a single glance answers "where is the nearest large pocket of fuel?"
5. Radical transparency in a genre full of implication. Every tooltip, the dashboard footer, and this description state plainly that levels are structural estimates, not exchange data.
═══════════════════════════════════════════════
🔶 HOW IT WORKS
— Swing anchors: confirmed pivot highs and lows define where crowds of entries concentrate.
— Tier projection: each anchor projects liquidation estimates at the distances implied by common leverage tiers (about 1%, 2%, 4%, and 10% from entry).
— Mass: each projection carries mass scaled by the volume z-score at the anchor — swings formed on climactic volume imply larger crowds.
— Clustering: projections landing near an existing cluster merge into it, shifting its weighted center and adding mass.
— Decay and death: mass decays every bar; weak clusters are pruned; swept clusters are consumed immediately.
— Rendering: each cluster draws a trailing heat band across the chart plus a three-layer intensity ladder at the right edge — length and brightness scale with mass; the strongest pool burns gold.
— Purge statistics: after each sweep, the ten-bar outcome is recorded in first-in-first-out sample sets, and reversal rates are displayed with sample counts.
Everything is computed on confirmed bars. Signals and clusters do not repaint. All drawings are capped for performance.
═══════════════════════════════════════════════
🔶 HOW TO USE IT
— Directional context: a heavy pool overhead with light fuel below suggests the path of least resistance is up (toward the fuel), and the Net Pull row quantifies this bias.
— Sweep-and-reversal trading: the classic use. Wait for price to purge a strong pool, check the dashboard's historical reversal rate for that direction on your symbol, and treat the purge as a candidate exhaustion point for your own entry method.
— Target selection: strong pools are natural take-profit magnets — many traders exit into the fuel rather than after it is spent.
— Risk placement: avoid resting stops just beyond a hot ladder; that is exactly where the market has an incentive to reach.
— Works on any symbol, but the leverage-tier logic is designed for crypto perpetual futures, where liquidation mechanics dominate intraday movement. Best on 15m to 4H.
═══════════════════════════════════════════════
🔶 SETTINGS
— Swing Anchor Length: pivot size defining the anchoring swings.
— Leverage Tiers: toggle 10x / 25x / 50x / 100x projections independently.
— Maximum Clusters, Merge Tolerance, Mass Decay: control the density and lifespan of the map.
— Purge flashes, heat ladders, magnet beam, and ladder length are individually toggleable.
— Statistics: sample cap, minimum samples to grade, shrinkage strength, Wilson z-score.
— Full color and dashboard customization.
═══════════════════════════════════════════════
🔶 ALERTS
— Approaching Magnet — price within half an Average True Range of an estimated pool.
— Upward Purge — an estimated short-liquidation pool was swept.
— Downward Purge — an estimated long-liquidation pool was swept.
═══════════════════════════════════════════════
🔶 FAQ
Q: Is this real liquidation data from exchanges?
A: No — and this matters. TradingView indicators cannot access exchange liquidation feeds or order books. Every level here is an estimate computed from price structure and the fixed mathematics of leverage. The tool is honest about this everywhere, and it compensates by measuring its own hit rate on your chart.
Q: Why do the estimated levels often line up with where price actually reverses?
A: Because liquidation math is public and mechanical. Everyone's 50x liquidation sits roughly two percent from entry, so crowded swings reliably produce crowded liquidation pockets — no private data required.
Q: Does it repaint?
A: No. Clusters form on confirmed pivots, purges are detected on confirmed bars, and consumed clusters stay consumed.
Q: Which markets and timeframes?
A: Designed for crypto perpetual futures on 15m–4H. The structural logic works elsewhere, but the leverage-tier assumptions are crypto-native.
Q: What do the reversal statistics mean?
A: After each purge, the tool records whether price moved back against the sweep over the next ten bars. Rates are shrunk toward fifty percent at low sample counts so early numbers cannot overstate the edge. They describe this chart's history only — they are not predictions.
═══════════════════════════════════════════════
🔶 CREDITS
The liquidation-level mapping concept was popularized by crypto derivatives analytics platforms; pivot structure detection is classical technique; the Wilson score interval is by Edwin B. Wilson (1927). The cluster model, volume-weighted mass and decay engine, purge state machine, self-auditing statistics, and all code in this script are original work. No third-party or open-source script code was reused.
═══════════════════════════════════════════════
🔶 LIMITATIONS
— All levels are estimates; actual liquidation prices vary with margin mode, maintenance margin, fees, and funding.
— The statistics describe historical behavior on the current chart only; past frequencies never guarantee future outcomes.
— On illiquid symbols or very low timeframes, swing anchors are noisier and clusters less meaningful.
═══════════════════════════════════════════════
🔶 DISCLAIMER
This indicator is a research and charting tool provided for educational purposes. It is not financial advice, and no statistic shown is a promise of future performance. Trading leveraged instruments involves substantial risk of loss. Always do your own analysis and manage risk responsibly. אינדיקטור

Bitcoin Halving Cycle PhasesBitcoin Halving Cycle Phases is a calendar-based visual indicator that highlights approximate Bitcoin halving cycle phase zones directly on the chart.
The indicator uses historical Bitcoin halving dates and predefined calendar phase boundaries to display different cycle regions, including Halving, Bullish, Bearish, Recovery, and Pre-halving phases. Future zones are projected using an approximate cycle length and are intended only as visual calendar references.
This script does not calculate price targets, buy or sell signals, trading entries, exits, stop losses, take profits, backtest results, or financial advice. The displayed future zones are approximate calendar projections only and should not be interpreted as forecasts or guaranteed market outcomes.
The indicator is designed for educational cycle visualization and long-term market context.
אינדיקטור

אינדיקטור

Bitcoin Cycle Highs and LowsOVERVIEW
The Bitcoin Cycle Highs and Lows indicator maps out the historical macro market cycle tops and bottoms of Bitcoin, dating back to 2011. In addition to serving as a visual map of historical market phases, the indicator features an algorithmic projection engine. This engine uses various statistical and geometric decay models to forecast the date and price of future macro highs and lows based on the asset's historical behaviour.
This tool is designed for macro-level market analysis, allowing traders to visualise diminishing returns, cycle duration trends, and phase retracements.
CHART ELEMENTS
When applied to a chart, the indicator plots several visual elements:
• Vertical Cycle Markers: Solid vertical lines identify the exact date of historical macro highs (Red) and macro lows (Lime).
• Price & Date Labels: Located at the anchor of each vertical line, detailing the exact recorded date and price (formatted automatically to the chart's active currency).
• Phase Arrows (Dashed Lines): Horizontal dashed lines connecting a low to the subsequent high (Bull Phase) or a high to the subsequent low (Bear Phase).
• Phase Statistics: Floating text labels positioned at the end of each Phase Arrow. These display the duration of the phase in days, the absolute price change, and the percentage move from the previous point.
PREDICTION MODELS
The indicator includes multiple distinct mathematical models for projecting future dates and prices.
Date Predictors:
• Previous bar count: Projects the next date by applying the exact duration of the most recent corresponding cycle.
• Average: Calculates the simple arithmetic average duration of all historical cycles of the same type.
• Weighted average: Averages previous cycle lengths but applies a mathematical recency bias, giving more weight to recent cycles to account for cycle duration stabilisation.
Price Predictors:
• Previous % move: Projects the next target by applying the exact percentage multiplier of the most recent corresponding cycle.
• Average: Projects the target using the geometric mean of all historical cycle multipliers, limiting the skew of extreme outliers.
• Diminishing gains: Analyses the cycle-over-cycle rate of change. It isolates peak-to-peak or trough-to-trough macro moves, calculates the historical decay in those percentage gains, and applies the decayed growth rate to project the next target.
• Fibonacci extension decay: Evaluates swing ratios by measuring the magnitude of a phase relative to the preceding phase (for example, how far a bull market extended past the previous bear market drop). It calculates the historical decay of that extension premium and applies it to the current swing.
SETTINGS AND INPUTS
• Predictions: Determines the number of future cycle highs and lows to project (0 to 9). Set to 0 to disable projections and only view historical data.
• Date predictor: Selects the algorithmic model used to project the X-axis (time) coordinate of future cycle points.
• Price predictor: Selects the algorithmic model used to project the Y-axis (price) coordinate of future cycle points.
• Bear/Bull market arrows: Toggles the visibility of the horizontal dashed lines and their accompanying statistical labels.
• Full height backgrounds: When true, vertical cycle markers extend infinitely across the Y-axis. When false, markers anchor precisely to the price level of the previous cycle phase, creating a stair-step visualisation.
• Ignore 2011 cycle: Excludes the extreme volatility and outliers of the 2011 cycle from the indicator's mathematical averages and trend decay calculations.
• Backtest # lows/highs: A testing feature that temporarily removes the most recent 1 or 2 historical cycle points from the dataset. This allows users to test the prediction models against known outcomes to evaluate their historical accuracy.
אינדיקטור

BTC Fundamental Value Hypothesis [OmegaTools]BTC Fundamental Value Hypothesis is a macro-valuation and regime-detection model designed to contextualize Bitcoin’s price through relative market-cap comparisons against major capital reservoirs: Gold, Silver, the Altcoin market, and large-cap equities. Instead of relying on traditional on-chain metrics or purely technical signals, this tool frames BTC as an asset competing for global liquidity and “store-of-value mindshare”, then estimates an implied fair value based on how BTC historically coexists (or diverges) from these benchmark universes.
Core concept: relative market-cap anchoring
The indicator builds a reference-based fair price by translating external market capitalizations into implied BTC valuation using a dominance framework. In practice, you choose one or more reference universes (Gold, Silver, Altcoins, Stocks). For each selected universe, the script computes how large BTC “should be” relative to that universe (dominance ratio), and converts that into an implied BTC price. The final fair price is the average of the implied prices from the enabled universes.
Two dominance modes: automatic vs manual
1. Automatic Dominance % (default)
When enabled, the model estimates dominance ratios dynamically using a 252-period simple moving average of BTC market cap divided by each reference market cap. This produces an adaptive baseline that follows structural changes over time and reduces sensitivity to short-term spikes.
2. Manual Dominance %
If you prefer a discretionary macro thesis, you can directly input dominance parameters for each reference universe. This is useful when you want to stress-test scenarios (e.g., “BTC should converge toward X% of Gold’s market cap”) or align the model with a specific long-term adoption narrative.
Reference universes and data construction
- BTC market cap: pulled from CRYPTOCAP:BTC.
- Gold and Silver market caps: derived from the corresponding futures symbols (GC1!, SI1!) multiplied by an assumed total above-ground quantity (constant tonnage converted to troy ounces). This provides a practical and tradable proxy for spot valuation context.
- Altcoin market cap: pulled from CRYPTOCAP:TOTAL2 (total crypto market excluding BTC).
- Stocks market cap proxy (Σ3): a deliberately conservative equity benchmark built from three mega-cap stocks (AAPL, MSFT, AMZN) using total shares outstanding (request.financial) multiplied by price. This avoids index licensing complexity while still tracking a meaningful slice of global equity beta/liquidity.
Valuation output: overvalued vs undervalued (log-based)
The valuation readout is expressed as a percentage derived from the logarithmic distance between BTC price and the model’s fair price. This choice makes valuation comparable across long time horizons and reduces distortion during exponential growth phases. A positive valuation indicates BTC trading below the model’s implied value (undervalued), while a negative valuation indicates trading above it (overvalued).
Oscillator: relative momentum and regime confirmation
In addition to fair value, the indicator includes a momentum differential oscillator built from RSI(50):
- BTC RSI is compared to the average RSI of the selected reference universes.
- The oscillator highlights when BTC strength is leading or lagging the broader macro benchmarks.
- Color is rendered through a gradient to provide immediate regime readability (risk-on vs risk-off behavior, expansion vs contraction phases).
Visualization and UI components
- Fair Price overlay: the computed fair price is plotted directly on the BTC chart for immediate comparison with spot price action.
- Valuation shading: the area between price and fair price is filled to visually emphasize dislocation and potential mean-reversion zones.
- Oscillator panel: a zero-centered oscillator with filled bands helps you identify persistent trend regimes versus transitional conditions.
- Summary table: a right-side table displays the current valuation (over/under) and, when Automatic mode is enabled, the live dominance ratios used in the model (BTC/GOLD, BTC/SILVER, BTC/ALTC, BTC/STOCKS).
How to use it (practical workflows)
- Macro valuation context: use fair price as a structural anchor to assess whether BTC is trading at a premium or discount relative to external liquidity baselines.
- Regime filtering: combine valuation with the oscillator to distinguish “cheap but weak” from “cheap and strengthening” (and the inverse for tops).
- Mean-reversion mapping: large, persistent deviations from fair value often highlight speculative extremes or capitulation zones; this can support systematic entries/exits, position sizing, or hedging decisions.
- Scenario analysis: switch to Manual Dominance % to model adoption outcomes, policy-driven shifts, or multi-year re-rating assumptions.
Important notes and limitations (read before use)
- This is a hypothesis-driven macro model, not a literal intrinsic value calculation. Results depend on dominance assumptions, proxies, and data availability.
- Gold/Silver market caps are approximations based on futures pricing and fixed supply constants; real-world supply dynamics, above-ground estimates, and spot/futures basis can differ.
- The Stocks (Σ3) benchmark is a proxy and intentionally not “the whole market”. It is designed to represent a large-cap liquidity reference, not total equity capitalization.
- Always validate signals with additional context (market structure, volatility regime, risk management rules). This indicator is best used as a macro layer in a broader decision framework.
Designed for clarity, macro discipline, and repeatability
BTC Fundamental Value Hypothesis by OmegaTools is built for traders and investors who want a clean, data-driven way to interpret BTC through the lens of competing asset classes and capital flows. It is particularly effective on higher timeframes (Daily/Weekly) where macro relationships are more stable and valuation signals are less noisy.
© OmegaTools, Eros אינדיקטור

אינדיקטור

The Oracle: Dip & Top Adaptive Sniper [Hakan Yorganci]█ OVERVIEW
The Oracle: Dip & Top Adaptive Sniper is a precision-focused trend trading strategy designed to solve the biggest problem in swing trading: Timing.
Most trend-following strategies chase price ("FOMO"), buying when the asset is already overextended. The Oracle takes a different approach. It adopts a "Sniper" mentality: it identifies a strong macro trend but patiently waits for a Mean Reversion (pullback) to execute an entry at a discounted price.
By combining the structural strength of Moving Averages (SMA 50/200) with the momentum precision of RSI and the volatility filtering of ADX, this script filters out noise and targets high-probability setups.
█ HOW IT WORKS
This strategy operates on a strictly algorithmic protocol known as "The Yorganci Protocol," which involves three distinct phases: Filter, Target, and Execute.
1. The Macro Filter (Trend Identification)
* SMA 200 Rule: By default, the strategy only scans for buy signals when the price is trading above the 200-period Simple Moving Average. This ensures we are always trading in the direction of the long-term bull market.
* Adaptive Switch: A new feature allows users to toggle the Only Buy Above SMA 200? filter OFF. This enables the strategy to hunt for oversold bounces (dead cat bounces) even during bearish or neutral market structures.
2. The Volatility Filter (ADX Integration)
* Sideways Protection: One of the main weaknesses of moving average strategies is "whipsaw" losses during choppy, ranging markets.
* Solution: The Oracle utilizes the ADX (Average Directional Index). It will BLOCK any trade entry if the ADX is below the threshold (Default: 20). This ensures capital is only deployed when a genuine trend is present.
3. The Sniper Entry (Buying the Dip)
* Instead of buying on breakout strength (e.g., RSI > 60), The Oracle waits for the RSI Moving Average to dip into the "Value Zone" (Default: 45) and cross back up. This technique allows for tighter stops and higher Risk/Reward ratios compared to traditional breakout systems.
█ EXIT STRATEGY
The Oracle employs a dynamic dual-exit mechanism to maximize gains and protect capital:
* Take Profit (The Peak): The strategy monitors RSI heat. When the RSI Moving Average breaches the Overbought Threshold (Default: 75), it signals a "Take Profit", securing gains near the local top before a potential reversal.
* Stop Loss (Trend Invalidated): If the market structure fails and the price closes below the 50-period SMA, the position is immediately closed to prevent deep drawdowns.
█ SETTINGS & CONFIGURATION
* Moving Averages: Fully customizable lengths for Support (SMA 50) and Trend (SMA 200).
* Trend Filter: Checkbox to enable/disable the "Bull Market Only" rule.
* RSI Thresholds:
* Sniper Buy Level: Adjustable (Default: 45). Lower values = Deeper dips, fewer trades.
* Peak Sell Level: Adjustable (Default: 75). Higher values = Longer holds, potentially higher profit.
* ADX Filter: Checkbox to enable/disable volatility filtering.
█ BEST PRACTICES
* Timeframe: Designed primarily for 4H (4-Hour) charts for swing trading. It can also be used on 1H for more frequent signals.
* Assets: Highly effective on trending assets such as Bitcoin (BTC), Ethereum (ETH), and high-volume Altcoins.
* Risk Warning: This strategy is designed for "Long Only" spot or leverage trading. Always use proper risk management.
█ CREDITS
* Original Concept: Inspired by the foundational work of Murat Besiroglu (@muratkbesiroglu).
* Algorithm Development & Enhancements: Developed by Hakan Yorganci (@hknyrgnc).
* Modifications include: Integration of ADX filters, Mean Reversion entry logic (RSI Dip), and Dynamic Peak Profit taking. אסטרטגייה

אינדיקטור

אינדיקטור

אינדיקטור

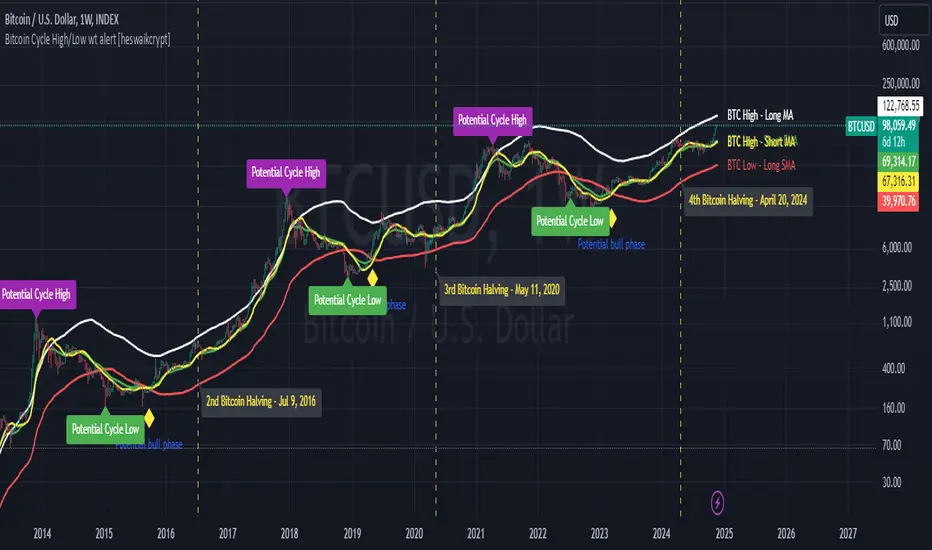
Bitcoin Cycle High/Low with functional Alert [heswaikcrypt]Introduction
Just as machines are fine-tuned for maximum efficiency, trading indicators must evolve to meet the demands of ever-changing markets.
Credit goes to the initial author, @NoCreditsLeft I only improved the existing Pi-cycle indicator with a functional alert and included a bull mode indicator in the script. The alert can help you get a live alert at candle close when the cycle tops, bottoms, and the potential bull phase switch occurs.
Philip Swift’s Pi Cycle Top Indicator is a brilliant example of leveraging mathematical relationships to signal critical turning points in Bitcoin’s price cycles. Historically, it has identified market and local tops with some relative accuracy, often within three days, as demonstrated in all the previous bull run cycles.
At its core, the Pi Cycle Indicator derives its name from the mathematical constant π (pi), achieved by using simple moving averages (MAs) in a specific ratio: 𝜋 = Long MA/short MA
The Bull mode switch is calculated using a crossover of the short exponentia moving average and the long moving average.
.
.
.
Knowing when Bitcoin reaches its top—and receiving timely alerts about it—is crucial for successful trading. The indicator is designed to signal;
Potential Bitcoin tops: Purple label
Potential Bitcoin bottoms : green Label, and
Parabolic swing : Yellow diamond shape (relating to the market switching to a potential bull mode)
"Please note: This indicator is tailored for Bitcoin using historical data analysis and should not be considered definitive. However accurate it might be."
Setting alerts
To set the alert conditions, select any alert function call to get alert whenever the conditions are met. The script is configured on dialy TF; you can set it on 1D or weekly TF.
Enjoy and Trade smartly אינדיקטור

2024 - Median High-Low % Change - Monthly, Weekly, DailyDescription:
This indicator provides a statistical overview of Bitcoin's volatility by displaying the median high-to-low percentage changes for monthly, weekly, and daily timeframes. It allows traders to visualize typical price fluctuations within each period, supporting range and volatility-based trading strategies.
How It Works:
Calculation of High-Low % Change: For each selected timeframe (monthly, weekly, and daily), the script calculates the percentage change from the high to the low price within the period.
Median Calculation: The median of these high-to-low changes is determined for each timeframe, offering a robust central measure that minimizes the impact of extreme price swings.
Table Display: At the end of the chart, the script displays a table in the top-right corner with the median values for each selected timeframe. This table is updated dynamically to show the latest data.
Usage Notes:
This script includes input options to toggle the visibility of each timeframe (monthly, weekly, and daily) in the table.
Designed to be used with Bitcoin on daily and higher timeframes for accurate statistical insights.
Ideal for traders looking to understand Bitcoin's typical volatility and adjust their strategies accordingly.
This indicator does not provide specific buy or sell signals but serves as an analytical tool for understanding volatility patterns. אינדיקטור

אינדיקטור

E9 PLRRThe E9 PLRR (Power Law Residual Ratio) is a custom-built indicator designed to evaluate the overvaluation or undervaluation of an asset, specifically by utilizing logarithmic price data and a power law-based model. It leverages a dynamic regression technique to assess the deviation of the current price from its expected value, giving insights into how much the price deviates from its long-term trend.
This indicator is primarily used to detect market extremes and cycles, often used in the analysis of long-term price movements in assets like Bitcoin, where cyclical behavior and significant price deviations are common.
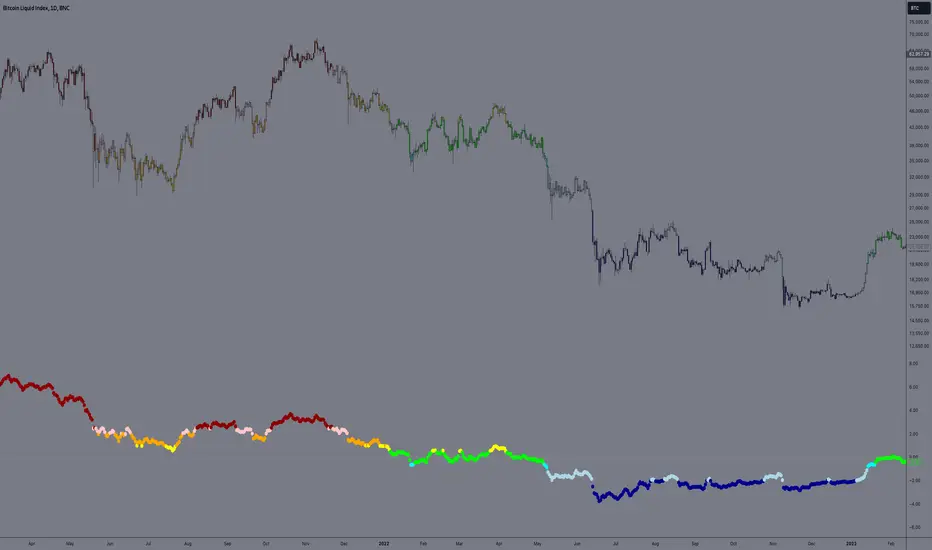
This chart is back from 2019 and shows (From left to right) 2018 Bear market bottom at $3.5k (Dark Blue) , following a peak at 12k (dark red) before the Covid crash back down to EUROTLX:4K (Dark blue)
Key Components
Logarithmic Price Data:
The indicator works with logarithmic price data (ohlc4), which represents the average of open, high, low, and close prices. The logarithmic transformation is crucial in financial modeling, especially when analyzing long-term price data, as it normalizes exponential price growth patterns.
Dynamic Exponent 𝑘:
The model calculates a dynamic exponent k using regression, which defines the power law relationship between time and price. This exponent is essential in determining the expected power law price return and how far the current price deviates from that expected trend.
Power Law Price Return:
The power law price return is computed using the dynamic exponent
k over a defined period, such as 365 days (1 year). It represents the theoretical price return based on a power law relationship, which is used to compare against the actual logarithmic price data.
Risk-Free Rate:
The indicator incorporates an adjustable risk-free rate, allowing users to model the opportunity cost of holding an asset compared to risk-free alternatives. By default, the risk-free rate is set to 0%, but this can be modified depending on the user's requirements.
Volatility Adjustment:
A key feature of the PLRR is its ability to adjust for price volatility. The indicator smooths out short-term price fluctuations using a moving average, helping to detect longer-term cycles and trends.
PLRR Calculation:
The core of the indicator is the calculation of the Power Law Residual Ratio (PLRR). This is derived by subtracting the expected power law price return and risk-free rate from the logarithmic price return, then multiplying the result by a user-defined multiplier.
Color Gradient:
The PLRR values are represented visually using a color gradient. This gradient helps the user quickly identify whether the asset is in an undervalued, fair value, or overvalued state:
Dark Blue to Light Blue: Indicates undervaluation, with increasing blue tones representing a higher degree of undervaluation.
Green to Yellow: Represents fair value, where the price is aligned with the expected power law return.
Orange to Dark Red: Indicates overvaluation, with increasing red tones representing a higher degree of overvaluation.
Zero Line:
A zero line is plotted on the indicator chart, serving as a reference point. Values above the zero line suggest potential overvaluation, while values below indicate potential undervaluation.
Dots Visualization:
The PLRR is plotted using dots, with each dot color-coded based on the PLRR value. This dot-based visualization makes it easier to spot significant changes or reversals in market sentiment without overwhelming the user with continuous lines.
Bar Coloring:
The chart’s bars are colored in accordance with the PLRR value at each point in time, making it visually clear when an asset is potentially overvalued or undervalued.
Indicator Functionality
Cycle Identification : The E9 PLRR is especially useful for identifying cyclical market behavior. In assets like Bitcoin, which are known for their boom-bust cycles, the PLRR can help pinpoint when the market is likely entering a peak (overvaluation) or a trough (undervaluation).
Overvaluation and Undervaluation Detection: By comparing the current price to its expected power law return, the PLRR helps traders assess whether an asset is trading above or below its fair value. This is critical for long-term investors seeking to enter the market at undervalued levels and exit during periods of overvaluation.
Trend Following: The indicator helps users identify the broader trend by smoothing out short-term volatility. This makes it useful for both momentum traders looking to ride trends and contrarian traders seeking to capitalize on market extremes.
Customization
The E9 PLRR allows users to fine-tune several parameters based on their preferences or specific market conditions:
Lookback Period:
The user can adjust the lookback period (default: 100) to modify how the moving average and regression are calculated.
Risk-Free Rate:
Adjusting the risk-free rate allows for more realistic modeling of the opportunity cost of holding the asset.
Multiplier:
The multiplier (default: 5.688) amplifies the sensitivity of the PLRR, allowing users to adjust how aggressively the indicator responds to price movements.
This indicator was inspired by the works of Ashwin & PlanG and their work around powerLaw. Thank you. I hall be working on the calculation of this indicator moving forward to make improvements and optomisations. אינדיקטור

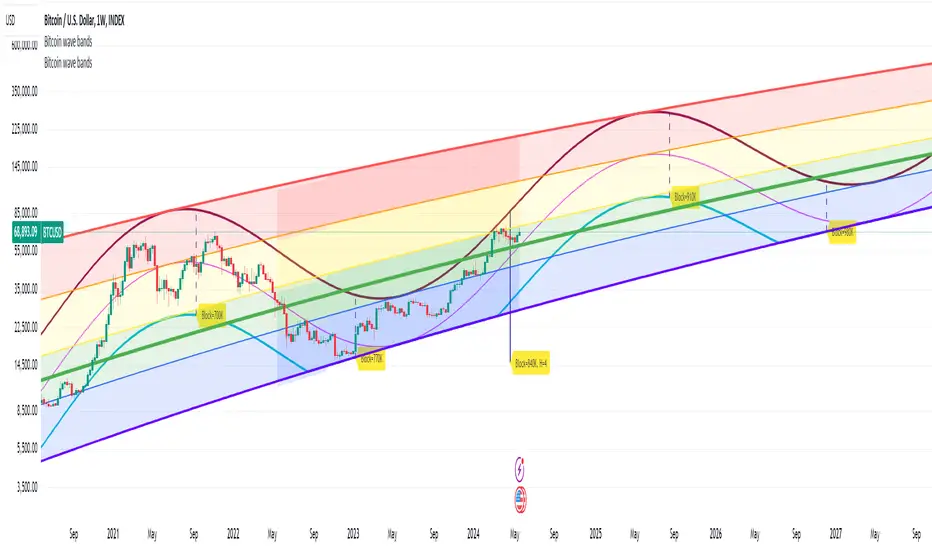
Bitcoin wave modelBitcoin wave model is based on the logarithmic regression model and the sinusoidal waves, induced by the halving events.
This chart presents the outcome of an in-depth analysis of the complete set of Bitcoin price data available from October 2009 to August 2023.
The central concept is that the logarithm of the Bitcoin price closely adheres to the logarithmic regression model. If we plot the logarithm of the price against the logarithm of time, it forms a nearly straight line.
The parameters of this model are provided in the script as follows: log (BTCUSD) = 1.48 + 5.44log(h).
The secondary concept involves employing the inherent time unit of Bitcoin instead of days:
'h' denotes a slightly adjusted time measurement intrinsic to the Bitcoin blockchain. It can be approximated as (days since the genesis block) * 0.0007. Precisely, 'h' is defined as follows: h = 0 at the genesis block, h = 1 at the first halving block, and so forth. In general, h = block height / 210,000.
Adjustments are made to account for variations in block creation time.
The third concept revolves around investigating halving waves triggered by supply shock events resulting from the halvings. These halvings occur at regular intervals in Bitcoin's native time 'h'. All halvings transpire when 'h' is an integer. These events induce waves with intervals denoted as h = 1.
Consequently, we can model these waves using a sin(2pih - a) function. The parameter determining the time shift is assessed as 'a = 0.4', aligning with earlier expectations for halving events and their subsequent outcomes.
The fourth concept introduces the notion that the waves gradually diminish in amplitude over the progression of "time h," diminishing at a rate of 0.7^h.
Lastly, we can create bands around the modeled sinusoidal waves. The upper band is derived by multiplying the sine wave by a factor of 3.1*(1-0.16)^h, while the lower band is obtained by dividing the sine wave by the same factor, 3.1*(1-0.16)^h.
The current bandwidth is 2.5x. That means that the upper band is 2.5 times the lower band. These bands are forming an exceptionally narrow predictive channel for Bitcoin. Consequently, a highly accurate estimation of the peak of the next cycle can be derived.
The prediction indicates that the zenith past the fourth halving, expected around the summer of 2025, could result in prices ranging between 200,000 and 240,000 USD.
Enjoy the mathematical insights! אינדיקטור

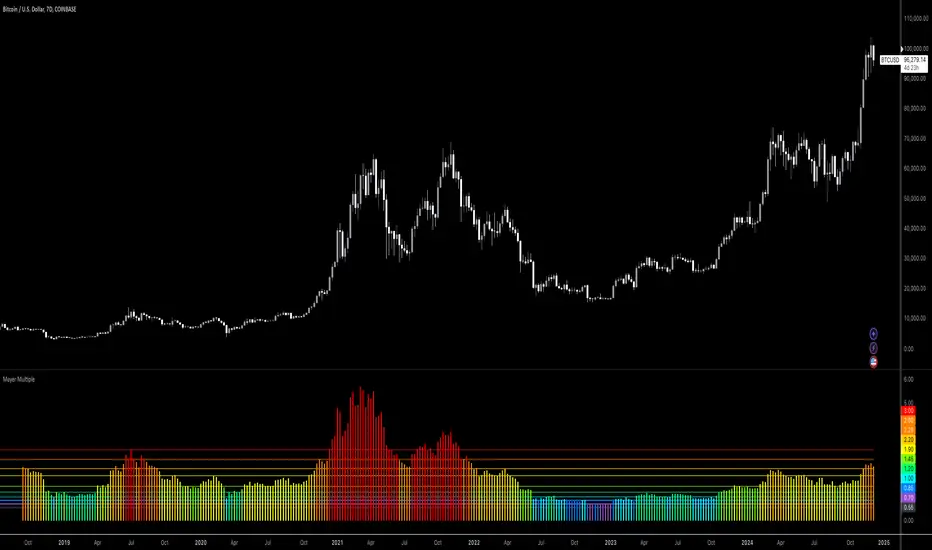
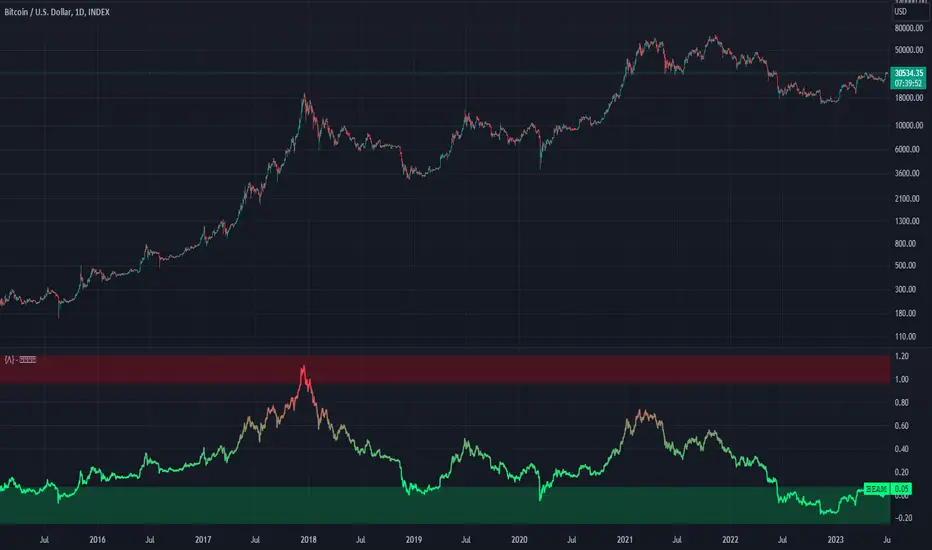
Bitcoin Economics Adaptive MultipleBEAM (Bitcoin Economics Adaptive Multiple) is an indicator that assesses the valuation of Bitcoin by dividing the current price of Bitcoin by a moving average of past prices. Its purpose is to provide insights into whether Bitcoin is under or overvalued at any given time. The thresholds for the buy and sell zones in BEAM are adjustable, allowing users to customize the indicator based on their preferences and trading strategies.
BEAM categorizes Bitcoin's valuation into two distinct zones: the green buy zone and the red sell zone.
Green Buy Zone:
The green buy zone in BEAM indicates that Bitcoin is potentially undervalued. Traders and investors may interpret this zone as a favorable buying opportunity. The threshold for the buy zone can be adjusted to suit individual preferences or trading strategies.
Red Sell Zone:
The red sell zone in BEAM suggests that Bitcoin is potentially overvalued. Traders and investors may consider selling their Bitcoin holdings during this zone to secure profits or manage risk. The threshold for the sell zone is adjustable, allowing users to adapt the indicator based on their trading preferences.
Methodology:
BEAM calculates the indicator value using the following formula:
beam = math.log(close / ta.sma(close, math.min(count, 1400))) / 2.5
The calculation involves taking the natural logarithm of the ratio between the current price of Bitcoin and a simple moving average of past prices. The moving average period used is a minimum of the specified count or 1400, providing a suitable historical reference for valuation assessment.
The resulting value of BEAM provides a standardized measure that can be compared across different time periods. By adjusting the thresholds for the buy and sell zones, users can customize BEAM to their preferred levels of undervaluation and overvaluation.
Utility:
BEAM serves as a tool for investors in the Bitcoin market, offering insights into Bitcoin's valuation and potential buying or selling opportunities. By monitoring BEAM, market participants can gauge whether Bitcoin is potentially undervalued or overvalued, helping them make informed decisions regarding their Bitcoin positions.
It is important to note that BEAM should be used in conjunction with other technical and fundamental analysis tools to validate signals and avoid relying solely on this indicator for trading decisions. Additionally, traders and investors are encouraged to adjust the threshold values based on their specific trading strategies, risk tolerance, and market conditions.
Credit: The BEAM (Bitcoin Economics Adaptive Multiple) indicator was originally developed by BitcoinEcon אינדיקטור

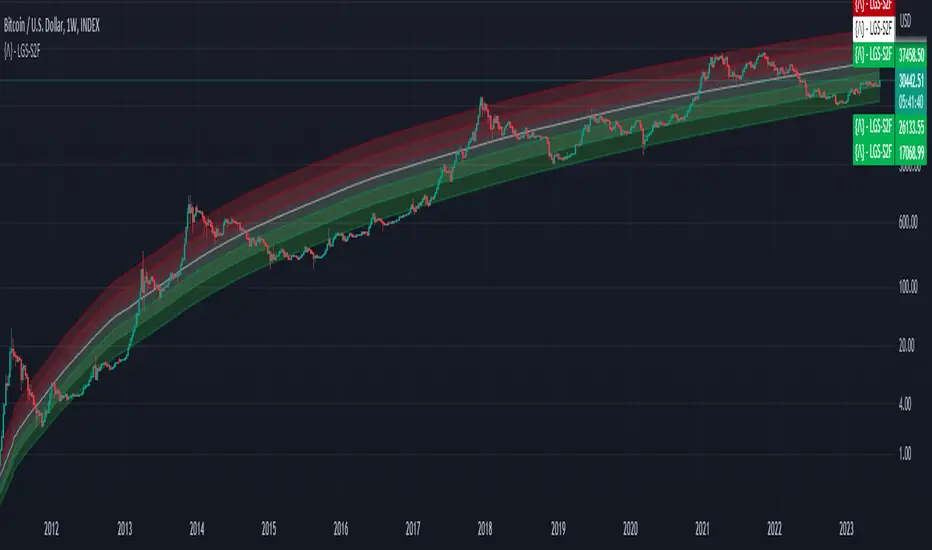
Bitcoin Limited Growth ModelThe Bitcoin Limeted Growth is a model proposed by QuantMario that offers an alternative approach to estimating Bitcoin's price based on the Stock-to-Flow (S2F) ratio. This model takes into account the limitations of the traditional S2F model and introduces refinements to enhance its analysis.
The S2F model is commonly used to analyze Bitcoin's price by considering the scarcity of the asset, measured by the stock (existing supply) relative to the flow (new supply). However, the LGS-S2F Bitcoin Price Formula recognizes the need for improvements and presents an updated perspective on Bitcoin's price dynamics.
Invalidation of the Normal S2F Model:
The normal S2F model has faced criticisms and challenges. One of the limitations is its assumption of a linear relationship between the S2F ratio and Bitcoin's price, overlooking potential nonlinearities and other market dynamics. Additionally, the normal S2F model does not account for external influences, such as market sentiment, regulatory developments, and technological advancements, which can significantly impact Bitcoin's price.
Addressing the Issues:
The LGS-S2F Bitcoin Price Formula introduces refinements to address the limitations of the traditional S2F model. These refinements aim to provide a more comprehensive analysis of Bitcoin's price dynamics:
Nonlinearity: The LGS-S2F model recognizes that the relationship between the S2F ratio and Bitcoin's price may not be linear. It incorporates a logistic growth function that considers the diminishing returns of scarcity and the saturation of market demand.
Data Analysis: The LGS-S2F model employs statistical analysis and data-driven techniques to validate its predictions. It leverages historical data and econometric modeling to support its analysis of Bitcoin's price.
Utility:
The LGS-S2F Bitcoin Price Formula offers insights for traders and investors in the cryptocurrency market. By incorporating a more refined approach to analyzing Bitcoin's price, this model provides an alternative perspective. It allows market participants to consider various factors beyond the S2F ratio alone, potentially aiding in their decision-making processes.
Key Features:
Adjustable Coefficients
Sigma calculation methods: Normal or Stdev
Credit:
The LGS-S2F Bitcoin Price Formula was developed by QuantMario, who has contributed to the field of cryptocurrency analysis through their research and modeling efforts. אינדיקטור

אינדיקטור

אינדיקטור